Insurance Solutions by Industry
Insurance Solutions for Retail Businesses in Cyprus
Retail exposure depends on what you sell, where you sell it and how much of it you hold. We help shop owners in Cyprus review the areas that fit their trading pattern.
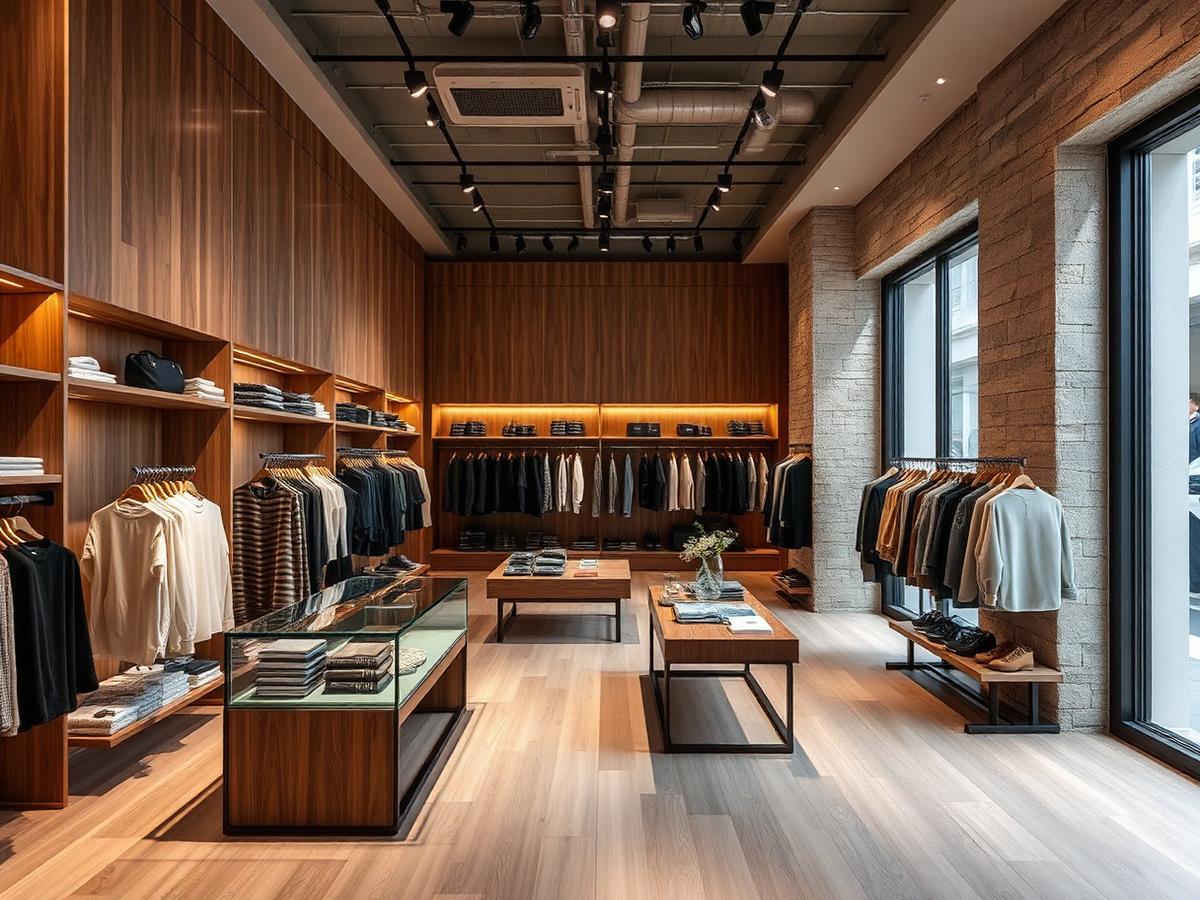
The nature of the sector
Retailers keep stock in shops or storage areas, and customers often handle products before buying. Stock levels may rise at busy times of year. Many retailers also sell online and arrange deliveries, so customer and payment data matter too. If a shop or online service must close, sales can stop while rent, wages and other costs continue.
6 Insurance Areas Worth Considering
Every business is different. These are six insurance areas commonly worth considering in this industry, depending on the activities and how the business operates.
Stock Insurance
Relates to damage, theft or spoilage of goods kept in the shop, storage areas or in transit. Stock levels at busy periods should be considered.
Property / Building & Contents Insurance
Relates to the building, if the business owns it, and to the equipment, furniture and other contents used every day in rented or owned premises.
Product Liability
Relates to claims where a product sold, imported or supplied by the retailer causes injury or damage.
Public Liability
Relates to accidents involving customers or visitors while they browse, handle or try products.
Cyber Insurance
Relates to cyberattacks, payment fraud and loss or exposure of customer and online-order data.
Business Interruption
Relates to lost sales and continuing costs if an insured incident stops shop or online trading.
Realistic examples
What could disrupt your business?
Fire and damage at the shop
A fire damages the premises, equipment and stock, and the shop has to close temporarily.
Theft of stock or equipment
Burglars break into the shop and steal merchandise or business equipment.
Water leak and damage to stock
A water leak damages stock, equipment or other items inside the shop.
Customer injured in the shop
A customer slips, falls or is injured in another way inside the shop.
A product causes injury to a customer
A product sold by the shop causes injury to a customer, and a compensation claim arises.
Temporary closure of the shop
A serious incident forces the shop to stay closed for a period, with sales and revenue lost.
These are illustrative examples to help explain risk. They are not statements about what any policy would or would not respond to — that always depends on the wording and the circumstances.
Our approach
Insurance starts with understanding your business.
We look at what you hold, when you hold most of it, how customers move through the shop, how much cash passes through and whether you also trade online. That gives a realistic view of where the business is exposed and what is worth reviewing first.
This page is general information about the sector. It does not describe policy terms, conditions or exclusions, and it is not a recommendation.
- What the business does
- How it operates day to day
- Premises and equipment
- Employees and the people you rely on
- Customers, clients and visitors
- Professional responsibilities
- Operational dependencies
- Risks that could materially affect you
Vesta Needs Review
Not sure what your business needs?
Start with the Vesta Needs Review. Answer a few simple questions about your business and we will help identify the areas that may be worth reviewing.
Prefer to speak with us?
If you would rather talk it through, tell us a little about your business and we will come back to you. No lengthy forms at this stage.
Insights